
A $100 casino deposit does not always mean exactly $100 leaves your bank account. Depending on the payment method, country, currency, and financial provider, additional charges may appear before or after the transaction settles.
Casino Payment Processing Fees can involve card processing, bank transfers, foreign transaction charges, currency conversion, or wallet-related costs. Some are absorbed by the casino, while others are passed to the customer by a financial provider.
Knowing the difference makes it easier to understand transaction statements and compare deposit or withdrawal methods without being distracted by one headline fee.
Why Casino Payments Need Processing
An online casino cannot normally move money directly from every player’s bank account into its own system.
It needs payment infrastructure.
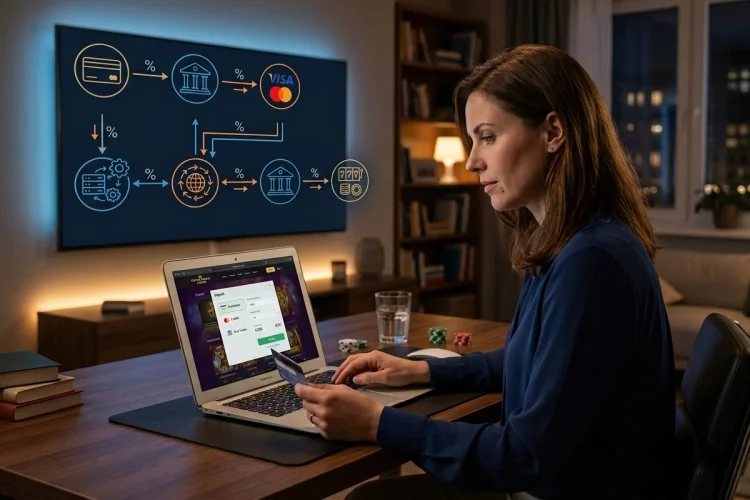
A card transaction may involve the casino, payment gateway, processor, acquiring bank, card network, and issuing bank.
Each participant performs a different function.
Payment processors manage the technical side of moving transaction information, while banks and card networks handle authorization and settlement.
According to Stripe, card-processing fees generally contain three main layers: interchange, network assessments, and processor markup.
The casino or merchant often pays these costs, but its pricing policy determines whether any portion is passed to the customer.
Interchange, Network Fees, and Processor Markups
Understanding merchant-side fees helps explain why some payment methods cost operators more than others.
1. Interchange
Interchange is generally paid to the bank that issued the customer’s card.
Rates can vary based on card type, location, transaction method, and other characteristics.
2. Network assessment
Card networks can collect their own assessment or network-related charges.
These tend to be smaller than interchange but still contribute to the total processing cost.
3. Processor markup
The payment processor then adds compensation for providing its technology and payment services.
Some processors combine these components into a flat rate.
For example, Stripe’s standard U.S. pricing currently advertises 2.9% plus $0.30 for successful domestic online card transactions. International cards and currency conversions can carry additional pricing.
That is an example of processor pricing, not a standard fee every online casino pays.
Why One Casino May Charge and Another May Not
Two casinos using similar payment methods can have different player-facing fee policies.
One operator may absorb its transaction costs.
Another might apply a fee to certain withdrawals or payment methods.
Large operators may also negotiate custom rates with processors based on transaction volume, risk profile, payment mix, and other commercial factors. Stripe notes that custom and volume-based pricing arrangements are available alongside standard rates.
This helps explain why there is no universal “casino card fee.”
Players should rely on the specific operator’s cashier terms rather than assuming that a fee seen at one casino applies everywhere.
Why Withdrawals Can Cost More Than Deposits
Deposits and withdrawals use different payment flows.
Casinos often want to make deposits convenient, so some absorb the cost of funding an account.
Withdrawals can require different payout infrastructure.
A bank transfer, card payout, instant payment, or e-wallet withdrawal may use another provider with its own pricing.
Some methods may also involve intermediary banks.
For instance, an international bank transfer can occasionally pass through multiple financial institutions before reaching the recipient. An intermediary may deduct a charge depending on the transfer structure and account agreement.
As a result, a withdrawal of $500 could theoretically arrive as slightly less even if the casino itself advertises no operator withdrawal fee.
The exact cause should be confirmed from the transaction record rather than guessed.
Foreign Transaction Fees Are Separate
A casino fee and a card issuer’s foreign transaction fee are different charges.
Suppose the casino does not charge anything for a $300 deposit.
If the card issuer applies a hypothetical 3% foreign transaction fee:
$300 × 3% = $9
The statement could show an effective cost of $309.
The CFPB explains that foreign transaction fees can apply when transactions occur with foreign merchants or involve foreign currencies. It also notes that charges can come from the issuer and, in some structures, another party participating in the currency conversion.
So “zero casino deposit fee” does not necessarily mean “zero total payment cost.”
Players should check their own card agreement.
International Cards Can Cost Merchants More
Cross-border payments can also increase costs on the merchant side.
Stripe currently lists an additional 1.5% for international cards under its standard U.S. card pricing, plus another amount when currency conversion is required.
Again, that is not a universal industry rate.
It does illustrate why accepting an overseas card can cost a merchant more than accepting a domestic card.
A casino may choose to absorb the difference, restrict certain card types, or structure fees differently.
This is one reason payment options can vary by location.
An operator may support Visa in one country while offering bank transfers, local instant payment systems, or e-wallets more prominently in another.
E-Wallets Have Their Own Fee Structures
E-wallet payments can feel simpler because users interact with one familiar account.
Behind the interface, however, the wallet still has its own pricing model.
PayPal’s U.S. merchant fee documentation currently distinguishes domestic from international commercial transactions and lists additional percentage-based fees for receiving some international payments. It also identifies currency conversion as a seperate pricing category.
The player does not automatically pay these merchant charges.
Consumer wallet fees can be structured differently.
The practical lesson is that users should check three things independently: what the casino charges, what the e-wallet charges, and whether a currency conversion takes place.
Otherwise, several small costs can become confused as one “processing fee.”
Currency Conversion Can Be Hidden Inside the Rate
Not every cost appears as a line item.
If the casino uses euros and the payment account uses dollars, money must be converted.
The conversion provider can use an exchange rate that includes a margin.
That margin changes the amount of currency received even when no separate “FX fee” appears on the receipt.
Some payment processors explicitly separate currency conversion pricing. Stripe’s current standard rates, for example, list an additional charge when currency conversion is required.
A player’s bank or wallet could use another model.
This is why comparing only stated transaction fees may give an incomplete picture.
The effective cost is the difference between the value expected at a reference rate and the amount actually charged or received.
Failed or Reversed Payments Can Be Complicated
Not every deposit completes successfully.
A bank may decline a gambling transaction, a processor might reject it, or technical verification may fail.
Usually, a declined authorization should not create the same completed-payment outcome as a settled transaction. However, temporary authorization holds can sometimes appear in an account before disappearing.
Reversals and refunds can also create confusion if currency conversion is involved.
If the original payment was converted between currencies, a later refund could occur when exchange rates have changed.
The refunded home-currency amount may therefore differ from the orginal charge even when the merchant returns the same transaction currency.
That difference should not automatically be interpreted as an extra casino fee.
How Small Charges Add Up
Consider a hypothetical $250 international casino deposit.
Suppose a payment method creates a 2% player-facing foreign transaction charge:
$250 × 2% = $5
Now imagine currency conversion adds an effective 1% cost:
$250 × 1% = $2.50
The combined additional cost becomes:
$5 + $2.50 = $7.50
The effective payment cost is therefore $257.50.
If this happened repeatedly across several deposits and withdrawals, small percentages could become more noticeable.
That makes the fee structure more relevant than a single transaction might suggest.
What to Check Before Choosing a Payment Method
Start with the casino cashier page.
Look for deposit fees, withdrawal costs, minimum and maximum amounts, processing times, and supported currencies.
Then check your own financial provider.
A card could have no annual fee but still charge for international transactions. An e-wallet may have free domestic transfers while applying different rules for currency conversion.
Also look at the final confirmation screen before approving a payment.
That is where any merchant-side surcharge or conversion amount should become easier to identify.
If the final amount looks unexpected, stop and review the transaction instead of assuming the difference is normal.
Casino Payment Processing Fees are not one single charge. They can involve merchant processing costs, withdrawal charges, bank fees, cross-border costs, wallet pricing, and currency conversion.
Some are absorbed by the casino while others reach the player directly. Before making a deposit or withdrawal, compare the casino’s cashier terms with your bank or payment provider’s rules and focus on the total amount ultimately charged.
